
Credit Card Debt Lawyer in Greensboro, NC
A default judgment is a lien on any real property you own in the county and can be enforced for years. An answer filed on time keeps every defense open: the amount, the paperwork, who owns the debt, and whether it is too old to sue on.
Tell us what happened
Sending this form does not make us your lawyer yet.
If you have been sued over a credit card in North Carolina, you generally have 30 days from being served to file an answer. Miss it, and the creditor can ask for a default judgment. Call (336) 379-0539 with the papers in hand, before the deadline runs.
Your Two Deadlines
| When | Deadline | Source |
|---|---|---|
| You are served with a summons and complaint | Answer within 30 days of service | G.S. 1A-1, Rule 12(a)(1) |
| A judgment is entered and you get a notice of your right to claim exempt property | Respond within 20 days of receiving the notice to claim exemptions | G.S. 1C-1603(a)(5) |
A small claims case before a magistrate works differently from a District Court lawsuit. Read the summons for the court date and call us right away.
How We Defend Credit Card Lawsuits
- Read the complaint and attachments. Who is the plaintiff, the bank or a debt buyer? What did they attach?
- Check the date of last payment. Actions on a contract generally must be brought within three years under G.S. 1-52(1).
- Test the paperwork. Debt buyers must meet specific NC filing and evidence rules, covered below.
- File the answer and any counterclaims. Collection-law violations can become counterclaims.
- Negotiate from strength. A properly defended case is what puts a realistic settlement or payment plan on the table.
No lawyer can promise a result. What a lawyer can do is make the creditor prove its case under the rules.
If a Debt Buyer Is Suing You
A debt buyer is a business that buys delinquent or charged-off consumer debt to collect it (G.S. 58-70-15(b)(4)). Many credit card suits are filed by debt buyers, not the original bank.
North Carolina requires a debt buyer to:
| Requirement | Statute |
|---|---|
| Send you written notice of intent to sue at least 30 days before filing, with the original creditor, original account number, a copy of the contract and an itemized accounting | G.S. 58-70-115(6) |
| Not sue on a debt it knows, or reasonably should know, is past the statute of limitations | G.S. 58-70-115(4) |
| Attach to the complaint the signed contract (or, for credit cards, documents from actual use of the card) and every assignment showing an unbroken chain of ownership with the original account number | G.S. 58-70-150 |
| Allege in the complaint that it is licensed and that the 30-day notice was sent | G.S. 58-70-145 |
| Before any default or summary judgment on a credit card debt, file authenticated business records showing the original account number, original creditor, itemized accounting, date of last payment, basis for interest and date the account was opened | G.S. 58-70-155(c) |
A complaint that fails G.S. 58-70-145 or 58-70-150 shall be dismissed on the debtor’s motion. A judgment entered without the 58-70-155 evidence is void and subject to vacatur (58-70-155(d)).
These protections only help if someone raises them. That is the reason to have a lawyer read the complaint before you answer it.
Collector Crossing the Line?
North Carolina prohibits debt collectors from, among other things:
- Threatening arrest, or threatening garnishment or seizure that is not actually intended and permitted by law (G.S. 75-51).
- Calling with unreasonable frequency, or at work against your instructions (G.S. 75-52).
- Misrepresenting the amount or status of the debt, or failing to disclose that they are collecting a debt (G.S. 75-54).
Violations of that article carry actual damages plus civil penalties of $500 to $4,000 per violation (G.S. 75-56(b)). That article does not cover collection agencies regulated under Chapter 58, which have their own rules.
Under federal law, a third-party debt collector must send a written notice of the debt, and if you dispute it in writing within 30 days, it must stop collecting until it verifies the debt (15 U.S.C. 1692g). A collector that violates the federal act can owe actual damages, additional damages up to $1,000, and attorney fees (15 U.S.C. 1692k(a)). Federal claims must be filed within one year of the violation (1692k(d)).
Can They Take My Wages or My Car?
North Carolina limits what a creditor can take even after it wins.
- Wages: G.S. 1-362 bars applying your earnings from the 60 days before the order to the judgment when they are needed to support your family.
- Exempt property: NC residents can keep, among other things, a residence interest up to $35,000, one vehicle up to $3,500, household goods up to set limits, and qualifying retirement accounts (G.S. 1C-1601).
You must claim these exemptions on time. The court notice gives you 20 days (G.S. 1C-1603). We prepare and file the claim.
What a Credit Card Defense Lawyer Costs
Cost depends on the amount sued for, the court, and whether the case settles or goes to hearing.
We tell you the fee before we start and put it in writing.
How to Choose a Credit Card Debt Lawyer in Greensboro
No firm in North Carolina may call itself the best. Ask any lawyer you are considering:
- Will you check the complaint against G.S. 58-70-145, 58-70-150 and 58-70-155?
- How will you confirm the date of last payment and the limitations period?
- Do collector violations give me a counterclaim?
- Are you a lawyer who can appear in court for me, or a settlement company?
- What will this cost if it settles, and if it does not?
If you own a business that is owed money, see our debt collection page for businesses. For other contract disputes, see breach of contract.
Our team
 Chad D. GarrettFounder
 Jason AycothPartner
 Sean OlsonPartner
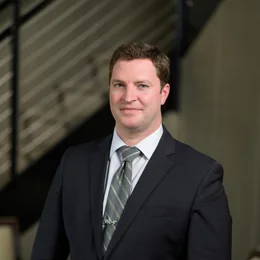 Brandon GoldsboroughCriminal Defense
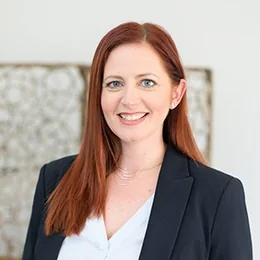 Stephanie GoldsboroughCriminal Defense
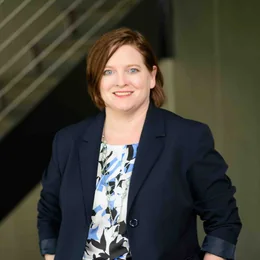 Rebecca ElliottCriminal Defense
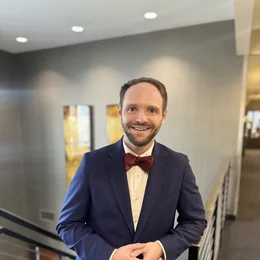 Patrick BidwellCriminal Defense
 Samantha HeplerCriminal Defense
What clients say
4.9 out of 5 from 587 Google reviews. A few recent ones:


Where we practice
Guilford County: Greensboro · High Point · Jamestown · Gibsonville · Summerfield · Oak Ridge · Pleasant Garden · Stokesdale · Whitsett · McLeansville · Sedalia
Also serving: Randolph, Forsyth, Alamance, Rockingham and Davidson Counties
Questions people ask
How long do I have to answer a credit card lawsuit in North Carolina?
Thirty days after you are served with the summons and complaint, under G.S. 1A-1, Rule 12(a)(1). A small claims case before a magistrate has a court date instead, so read the summons and call right away.
What happens if I ignore a credit card lawsuit?
The creditor can seek a default judgment. A docketed judgment becomes a lien on real property you own in that county and can be enforced for years.
What is the statute of limitations on credit card debt in NC?
Actions on a contract generally must be brought within three years under G.S. 1-52(1). A debt buyer may not sue on a debt it knows or should know is time-barred under G.S. 58-70-115(4).
What does a debt buyer have to prove in North Carolina?
It must attach the contract or card-use documents and every assignment showing ownership under G.S. 58-70-150. Before default or summary judgment on a credit card debt, it must file authenticated records listed in G.S. 58-70-155(c).
Can a credit card company garnish my wages in North Carolina?
G.S. 1-362 bars applying your earnings from the 60 days before the order to the judgment when they are needed to support your family. Other property may be reachable unless it is exempt.
What property can I keep if I lose?
NC residents can claim exemptions under G.S. 1C-1601, including a residence interest up to $35,000, one vehicle up to $3,500 and qualifying retirement accounts. You must respond to the exemption notice within 20 days under G.S. 1C-1603.
Can I stop a debt collector from harassing me?
NC law bars threats, harassment and deception by debt collectors under G.S. 75-51 through 75-54, with penalties under 75-56. Federal law gives you 30 days to dispute a debt in writing under 15 U.S.C. 1692g.
Should I call the creditor myself first?
Talk to a lawyer before you admit the amount or agree to a payment, especially on an older debt. What you say can affect your defenses.
Do you also represent businesses collecting debts?
Yes, on a separate page. Every matter gets a conflict check before we take it.
Talk to a lawyer today
Garrett, Walker, Aycoth & Olson, Attorneys at Law
317 South Greene St, Greensboro, NC 27401
(336) 379-0539 · answered live, 24 hours
Free consultation · Se habla español
This page provides general information about North Carolina and federal law, including G.S. 1A-1 Rule 12, 1-52, 1-362, 1C-1601, 1C-1603, 58-70-15, 58-70-115, 58-70-145, 58-70-150, 58-70-155, 75-50 through 75-56, and 15 U.S.C. 1692a, 1692g and 1692k. It is not legal advice.